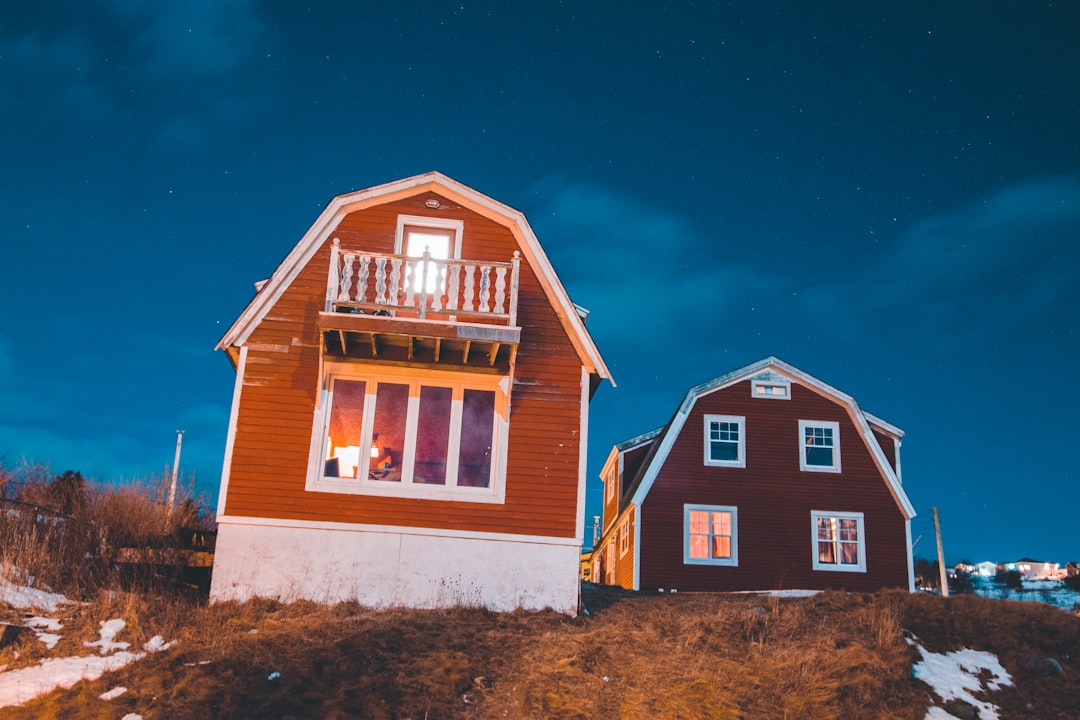

The housing inventory story for 2027
In a recent episode, Editor in Chief Sarah Wheeler and Lead Analyst Logan Mohtashami discuss upcoming trends in mortgage rates and housing inventory leading into 2027.
1,175 stories
Mortgage, housing and bond-market headlines from across the web, gathered in one place. Click a headline to read the full story on the publisher's site.
Showing 649–672 of 1,175
In a recent episode, Editor in Chief Sarah Wheeler and Lead Analyst Logan Mohtashami discuss upcoming trends in mortgage rates and housing inventory leading into 2027.
Alliance Reverse Mortgage CEO Ron Kamler highlights that credit unions have been hesitant to offer reverse mortgages, originating only 81 out of nearly 36,000 loans in the last year. He believes that while there are concerns regarding… reputational risk and product complexity, these risks can be managed through proper execution and partnerships with specialists, which may prevent members from seeking reverse mortgage options elsewhere.
Despite a perceived stall in the housing market, Smokey Garrett from Keller Williams suggests it's still active, albeit under different circumstances. Buyers are cautious about affordability, and sellers are adjusting their expectations.… Successful agents are focusing on providing clear guidance and understanding client needs. Growth for brokerages includes assessing market share and agent productivity, while agents must evolve to offer value beyond transactions. Garrett notes the potential of AI to enhance efficiency without replacing personal relationships, emphasizing the importance of adapting together to maintain industry value for consumers.
The article discusses the evolving challenges in the mortgage industry over the past two decades, highlighting the gap between loan origination and risk understanding. It reflects on lessons learned from the 2006 housing crisis, emphasizing… the importance of loan quality, verification, and accountability. The refinancing boom of 2020-2021 tested industry capacity, shifting focus to cost and productivity as interest rates rose. The rise of AI in the mortgage process presents new opportunities and challenges, and the industry's historical experiences make the approach to AI adoption critical.
The article discusses the challenges faced by lenders in utilizing down payment assistance (DPA) programs, which average around $18,000. It highlights the need for consistent data and workflows, advocating for a MISMO data standard that… would allow DPA eligibility and benefits to be seamlessly integrated into loan origination and point-of-sale systems. The author argues against the idea of a universal DPA program, suggesting instead that a unified standard would be more effective in addressing the fragmentation and operational difficulties associated with DPA.
Logan Mohtashami is a prominent analyst in the mortgage and housing sector, known for his deep insights into the U.S. economy and real estate market. As the lead analyst for HousingWire and a frequent contributor to its podcast, he… leverages over 20 years of experience to simplify complex economic data. His expertise has made him a popular figure in media, including regular appearances on CNBC.
Mortgage pricing is expected to be stable or slightly lower, as bond yields have dipped this morning. Despite numerous hawkish statements from the Federal Reserve, there has been little impact on the bond market or oil prices, even amidst… ongoing news updates.
Housing inventory was 898,139, down 3,973. The median list price was $435,000, down $1,490. Homes spent a median of 70 days on the market, unchanged, while 42.89% of listings had price reductions, up 0.06 percentage points.
The mortgage industry is undergoing a significant transformation as traditional growth in purchase and refinance lending slows. Factors such as rising affordability pressures, demographic changes, and high homeowner equity are driving this… shift. A new market is emerging focused on the $14.5 trillion in home equity held by homeowners aged 62 and older, leading to increased demand for liquidity solutions like reverse mortgages and home equity products. Lenders are beginning to view these products as strategic components of a lifecycle lending model aimed at fostering long-term relationships with borrowers and managing housing wealth, rather than just competing for diminishing purchase volume.
Flávia Furlan Nunes is HousingWire’s mortgage reporter, with more than a decade of experience at major Brazilian economic outlets and a master’s degree in Economics and Business Reporting from Columbia University.
The Mortgage Bankers Association (MBA) projects a 5% decline in total single-family mortgage origination volume for 2027, dropping to $1.99 trillion, primarily due to sustained mortgage rates above 7% driven by inflation and potential… Federal Reserve rate hikes. The MBA's chief economist highlights that while rates may peak, they are unlikely to decrease significantly.
Flávia Furlan Nunes is HousingWire’s mortgage reporter. She previously worked for Brazilian economic news outlets for over a decade and holds a master’s degree in Economics and Business Reporting from Columbia University.
HHHunt has announced a leadership transition set for July 1, 2027, where CFO Ann Kelly will become the CEO, taking over from Buck Hunt, who will remain chairman and focus on a new hospitality venture. The executive leadership team will… include Steve Brant as CFO and Steve Fritz as COO, emphasizing a finance and operations-focused management approach at the homebuilding and real estate company.
The article discusses how real estate brokerages are shifting their focus from traditional competitive strategies like commission splits and brand recognition towards more agent-centric models that provide tangible support and resources for… agents. It highlights the need for brokerages to help agents build sustainable businesses with ongoing guidance and professional development, moving away from the 'sink-or-swim' approach that has limited agent potential. The emphasis is on retaining agents through valuable daily support rather than just recruiting them.
The article discusses the current state of bond volatility, which has kept the 10-year yield around the critical level of 5.35%. Mortgage rates are currently at 7.48%, with spreads widening to 2.12%. Despite fluctuating economic conditions,… the 5.35% yield has stabilized for now, raising questions about whether mortgage rates have peaked for 2026 or if they could rise to 8% or more in the near future due to ongoing uncertainties.
The mortgage industry faced significant challenges in 2022 due to higher mortgage rates, leading to reduced interest from borrowers and a wave of bank consolidations. This trend is likely to continue into the first half of 2023, but there… is optimism for potential improvement later in the year. Professionals in the mortgage origination field are encouraged to stay updated through resources like HousingWire, which offers extensive coverage on the topic.
HousingWire's coverage of the mortgage news highlights the current changes in the housing market, focusing on the impact of Federal Reserve policies on mortgage rates and the broader economic landscape. As we approach 2023, analysis shows… that the economic conditions may evolve, particularly regarding potential job losses. Moreover, innovations in mortgage lending, such as loanDepot's launch of an automated underwriting engine, are also covered to help industry professionals stay informed and make strategic decisions.
TransUnion and Equifax have unveiled new mortgage credit tools designed to help mortgage lenders save costs by separating the process of accessing borrower credit files from purchasing credit scores. This change allows lenders to initially… review credit information without incurring immediate costs for score purchases, with the option to pay for scores later if necessary. TransUnion also introduced a new feature called First Look Functionality for Mortgage, which enhances the ability of lenders to assess credit insights before scoring.
President Donald Trump has formed a White House committee to investigate Federal Reserve Governor Lisa Cook over allegations of falsifying bank documents to secure favorable mortgage terms. This action, following referrals from the FHFA… director and a Justice Department investigation, signifies a continuing effort to challenge Cook's position on the Fed Board, raising questions about presidential authority over the independent institution.
Ashton Woods, a major private homebuilder, reported a 6.7% drop in orders and a 3.6% decrease in average selling price (ASP) to $346,000, with gross margins falling to 22.7% in Q1 2027. In a recent earnings call, executives emphasized their… preference to avoid sacrificing margins for volume, indicating they would rather sell slower than compromise on profitability amidst rising affordability pressures in the housing market.
eXp Realty's 2026 eXp Con in Salt Lake City attracted around 4,000 agents from 20 countries to discuss challenges in the housing market due to rising mortgage rates. The event showcased new tools for agents and announced a partnership with… Newrez for a new mortgage venture, while the atmosphere remained positive despite market difficulties.
The article discusses insights from HW+ on the mortgage and real estate sectors, highlighting the importance of proper workflow governance and process mapping in lending operations. Larry Bailey, CEO of Mortgage Workflow Partners,… emphasizes that many lenders implement AI and automation haphazardly, which can lead to increased operational risks. Additionally, the piece gives a brief note on the examination of state investments in home- and community-based services for older adults and mentions a new homebuilding venture by real estate developer Art Falcone.
In the second quarter of 2026, housing wealth among homeowners aged 62 and older reached a record $15.34 trillion, surpassing $15 trillion for the first time. This increase, of $430 billion in senior home values, was somewhat offset by an… additional $30 billion in mortgage debt. The data is sourced from the National Reverse Mortgage Lenders Association (NRMLA) and RiskSpan's Reverse Mortgage Market Index (RMMI), which tracks trends in senior home values and home equity since 2000.
Benutech's analysis of nearly 35,000 active reverse mortgages found significant discrepancies between servicing records and public title data, resulting in 10.42% D grades and 11.56% F grades, which included unrecorded transfers and… occupancy errors. The findings indicate a potential risk management issue for reverse mortgage servicers, as many serious issues were not flagged, highlighting the importance of accurate title records in the reverse mortgage marketplace.
Disclaimer
LoanGlass is not a lender. LoanGlass (formerly mortgage-rates.ai) is an independent site that helps borrowers compare mortgage rates. We are not a lender, mortgage broker or financial advisor, and we are not registered with the Nationwide Multistate Licensing System (NMLS). Nothing on this site is an offer to lend.
Where the rates come from
Every day we collect the rates that more than 1000 lenders publish on their own websites, and we show them as published. Averages, ranges, charts and forecasts are our own calculations, and forecasts may be wrong. Lender records, reviews and market data come from public sources such as the NMLS, NCUA, OCC, HMDA filings, the U.S. Treasury, Freddie Mac and Bankrate. We work to keep it all accurate, but it may contain errors.
Your rate may differ
The rate a lender offers you depends on your credit, income, down payment, loan and property, and you may not qualify for every rate shown. Payments shown with rates are principal and interest only; taxes and insurance are extra. Calculator results are estimates. Ask lenders for an official Loan Estimate before you decide.
Promoted listings
Lenders are included for free, but some pay for promotion. Promoted lenders are marked "Promoted" and appear above other lenders in rate results, whatever their rate. Paid placement can also decide the order between lenders that show the same rate. Paying never changes the rates a lender publishes.
Questions or corrections?
To report an error or have your institution's rates included, email content@loanglass.com.
All logos, trademarks and brand names belong to their owners.
What would make LoanGlass more useful to you?
We appreciate your feedback.
We use cookies and similar technologies to improve your experience, analyze site usage, and deliver personalized content. By clicking "Accept", you agree to the storing of cookies on your device in accordance with our Privacy Policy. You can manage your cookie preferences at any time.